Everything we know, made available
Regulatory updates, practical guides, and reference material for anyone building a lending business in India.
Blog & Insights
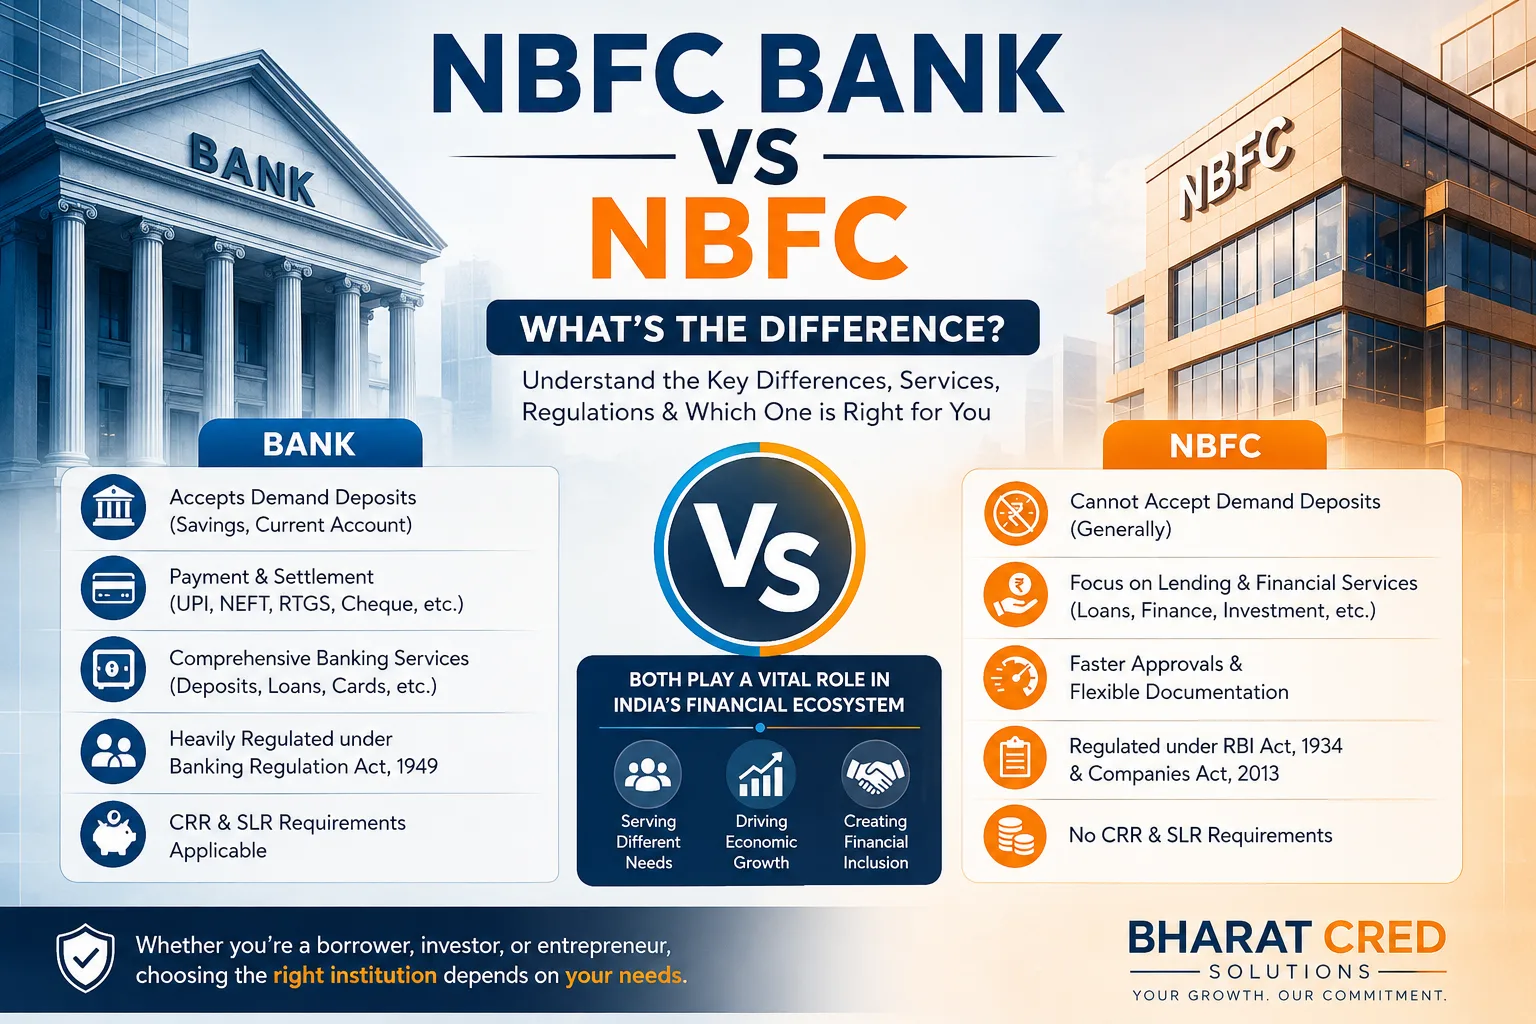
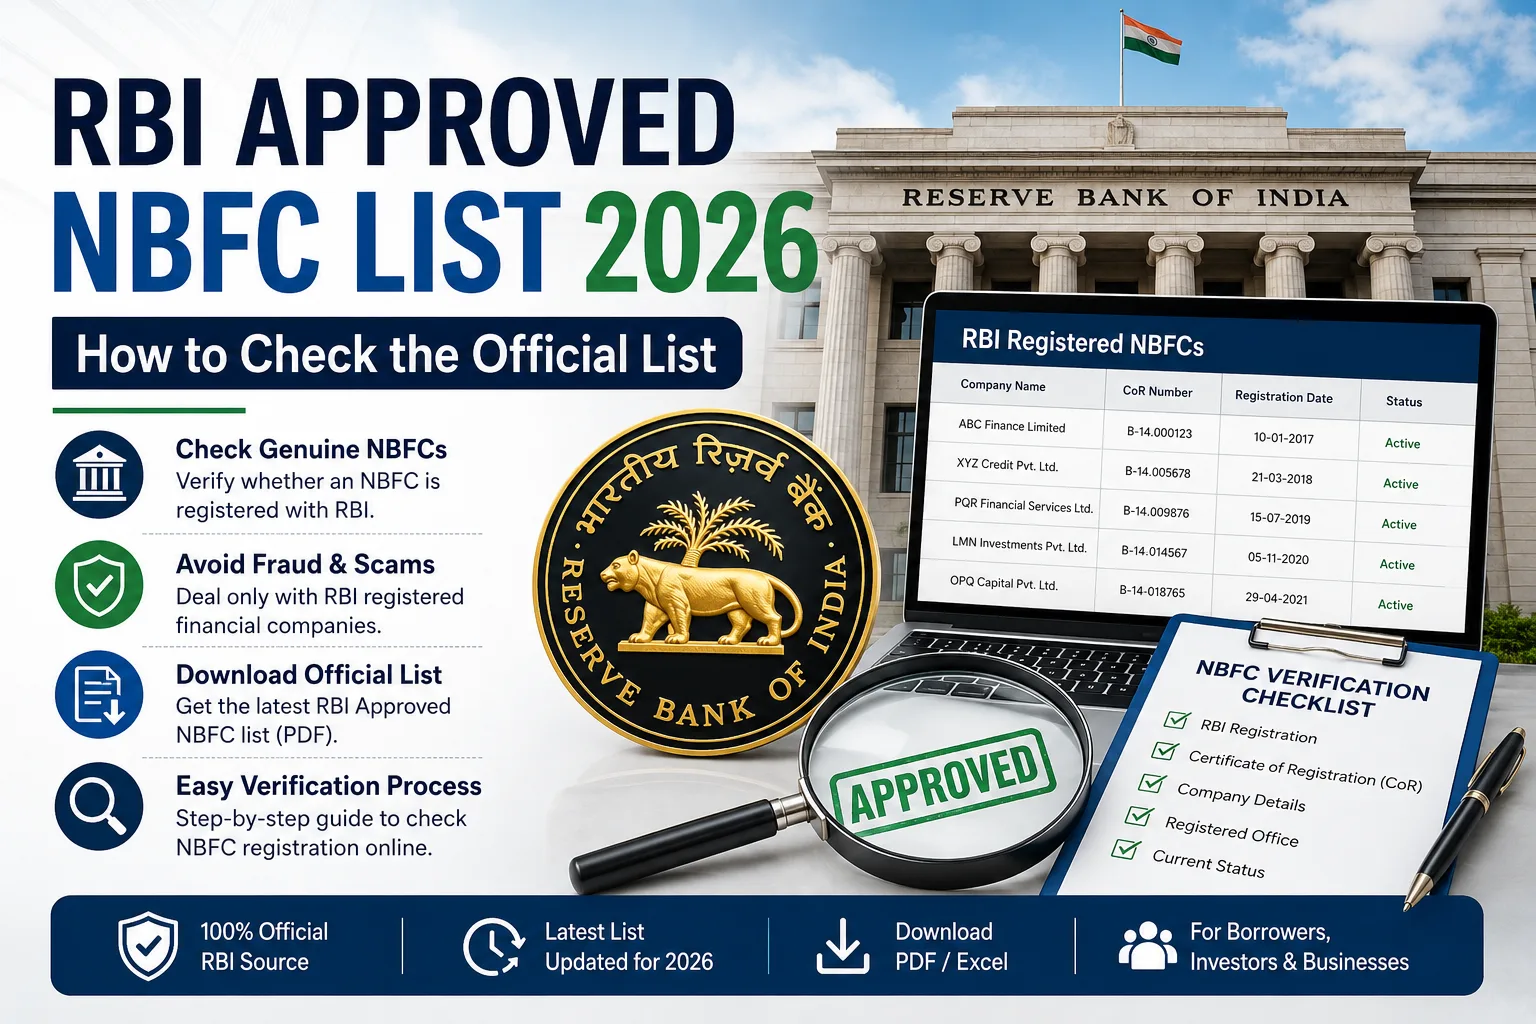
RBI Circulars
Master Direction on NBFC Scale Based Regulation
RBI/DoR/2023-24 · Consolidated Master DirectionSets out the layered regulatory framework for NBFCs based on size, activity, and perceived risk — the foundational reference for NBFC compliance.
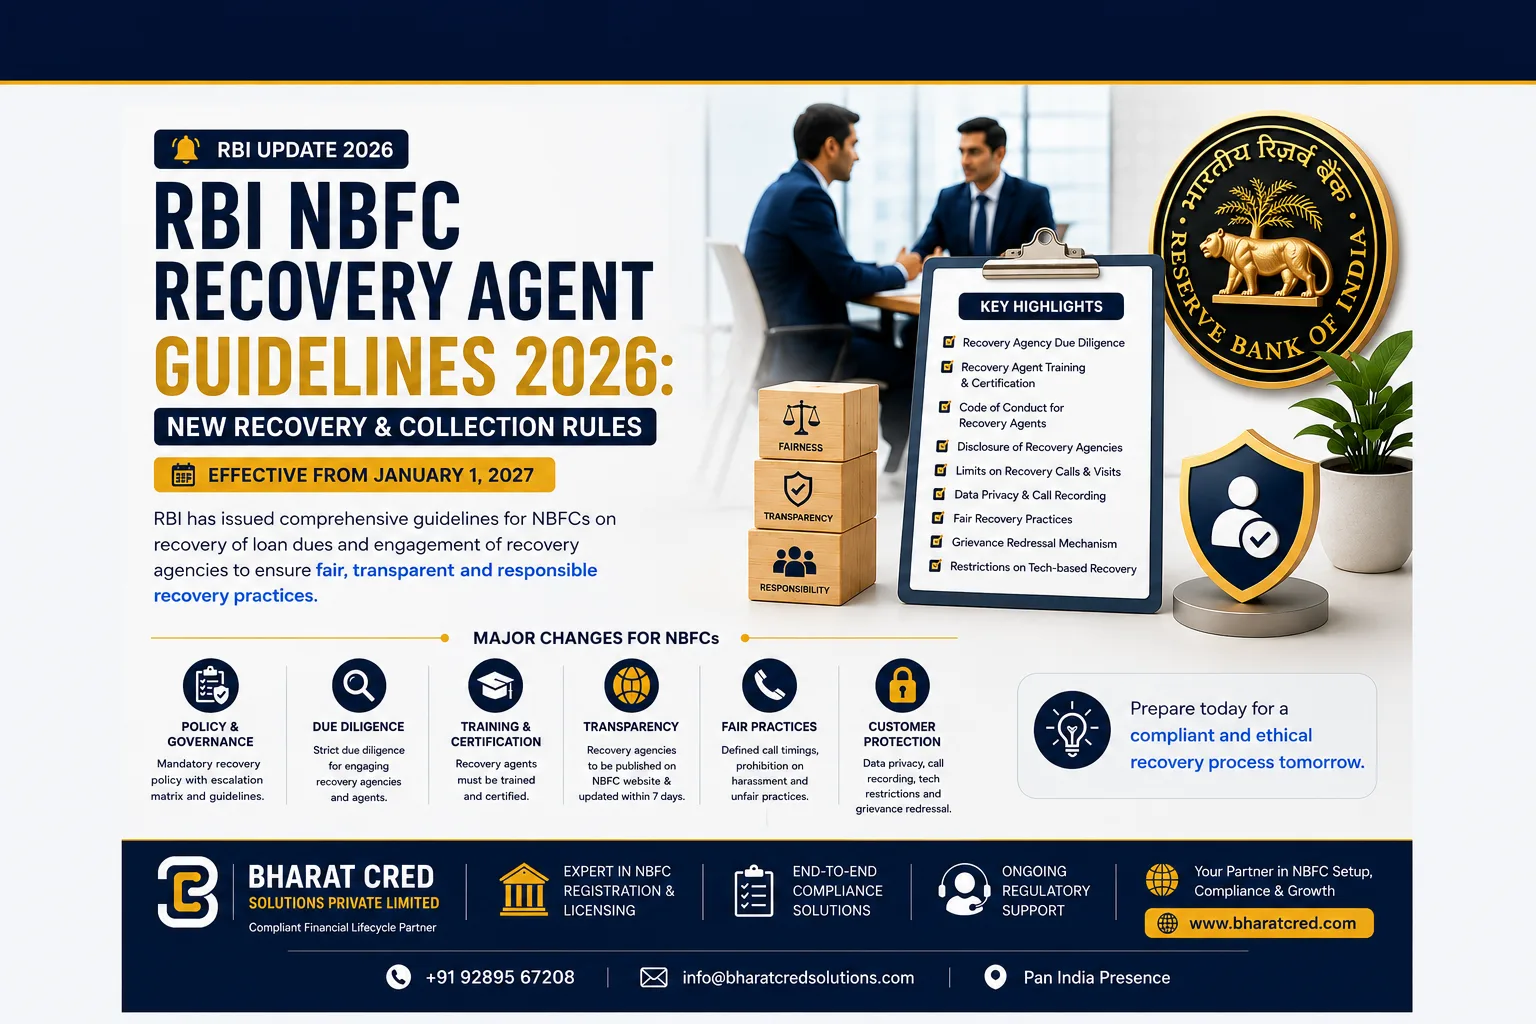
Fair Practices Code for NBFCs
RBI/DoR/FPC · Master DirectionGoverns disclosure, recovery conduct, and grievance redressal standards that every NBFC's policies must reflect.
KYC Master Direction
RBI/DBR/KYC · Master DirectionDefines customer due diligence, risk categorization, and periodic KYC update requirements applicable to regulated lenders.
Guidelines on Digital Lending
RBI/DoR/Digital Lending · Master DirectionSets out disclosure, data governance, and outsourcing requirements specific to digital lending journeys and loan service providers.
Guides & Download Center
Answers to common questions
How long does NBFC registration typically take?+
Timelines vary based on entity readiness and RBI's review cycle, but the biggest driver is how complete your application is on first filing. We structure documentation upfront specifically to minimize clarification rounds.
What is the minimum capital required to start an NBFC?+
RBI mandates a minimum Net Owned Fund for NBFC registration, with specific thresholds depending on the type of NBFC. We assess your business model and map the exact capital structure required on a strategy call.
Do you only work with new NBFCs, or established ones too?+
Both. We support founders launching a new NBFC from scratch, as well as established NBFCs and banks that need technology, compliance, collections, or recovery support at scale.
Can you manage collections without taking over our entire operations?+
Yes. Collections and recovery can be engaged as a standalone service, layered onto your existing operations, or run as part of a fuller BPO engagement — the scope is defined around what you actually need.
How does pricing work for an engagement?+
Pricing depends on scope — a one-time NBFC licensing engagement is structured differently from an ongoing compliance or collections retainer. We'll walk through options specific to your requirement on a call.
Do you work with businesses outside major metro cities?+
Yes, our field collections and BPO operations network extends across multiple states, and our advisory and technology engagements are delivered remotely regardless of location.